联邦第九巡回法院分歧裁决:加州气候披露法范围一、二照常执行,范围三与气候风险报告可能违宪
旧金山—美国联邦第九巡回上诉法院11月9日就加州两部气候披露法作出分歧裁决:年营收逾10亿美元企业依 SB 253 申报范围一与范围二温室气体排放的要求照常执行,首个申报截止日仍为11月10日;但同一法律的范围三(价值链)排放披露,以及 SB 261 的气候相关财务风险报告,被合议庭认定可能违反美国宪法第一修正案,案件发回洛杉矶联邦地区法院处理。
这起诉讼名为 Chamber of Commerce v. Sanchez,案号25-5327,由美国商会、美国农场局联合会等商业团体2024年1月提起,指两部法律强迫企业就争议议题发言。SB 253 全称《气候企业数据问责法》,适用于在加州经营、年营收逾10亿美元的企业,裁决书估计涵盖约1,971家公司,要求逐年披露排放:范围一为企业自身直接排放,范围二为外购能源的间接排放,范围三为供应商与客户等价值链上下游排放。SB 261 适用于年营收逾5亿美元的企业,估计约2,675家,要求每两年发布气候相关财务风险报告。两部法律均由州长纽森2023年签署,加州由此成为全美首个立此要求的州。
三人合议庭认为,范围一与范围二披露的是企业自身经营的事实信息、与资本交易相关,属商业言论,经中间审查后州政府胜诉可能性较大,因此不予叫停,2025年度数据的申报截止日11月10日不变。范围三则与申报企业自身经营的联系过于松散,不属商业言论,且可能通不过严格审查;SB 261 要求企业就「政治上敏感的议题」作出主观、前瞻性判断,属强迫非商业言论。合议庭据此推翻地区法院拒绝初步禁令的裁定,并把范围三条款能否与 SB 253 其余部分分割的问题发回地区法院决定。法官 Bennett 对判决部分同意、部分反对,认为两部法律都应整体先行叫停。
本裁决属初步禁令阶段的判断,不是案件的终局判决;当事人可在14天内申请复核或全院法官联席审理,也可上诉至美国最高法院。加州空气资源委员会(CARB)负责执行 SB 253 的申报计划,本站10月曾报道该法规10月12日生效、首批排放报告11月10日截止。
(来源:美国联邦第九巡回上诉法院)
Ninth Circuit Splits on California Climate Disclosure Laws: Scope 1 and 2 Reporting Proceeds, Scope 3 and SB 261 Likely Unconstitutional
SAN FRANCISCO — A divided three-judge panel of the U.S. Court of Appeals for the Ninth Circuit ruled on November 9 on California's two climate disclosure laws: reporting of Scope 1 and Scope 2 greenhouse gas emissions under SB 253 for companies with annual revenues over $1 billion proceeds as scheduled, with the first filing deadline still November 10, while SB 253's Scope 3 value-chain disclosure requirement and SB 261's climate-related financial risk reports were held likely unconstitutional under the First Amendment, with the case remanded to the federal district court in Los Angeles.
The case, Chamber of Commerce v. Sanchez, No. 25-5327, was brought in January 2024 by the U.S. Chamber of Commerce, the American Farm Bureau Federation and other business groups, which argued the laws compel speech on a contentious subject. SB 253, the Climate Corporate Data Accountability Act, covers an estimated 1,971 companies doing business in California with revenues above $1 billion and requires annual emissions reporting: Scope 1 covers a company's own direct emissions, Scope 2 emissions from purchased energy, and Scope 3 emissions across its value chain. SB 261 covers an estimated 2,675 companies with revenues above $500 million and requires biennial climate-related financial risk reports. Governor Gavin Newsom signed both laws in 2023, making California the first state to impose such requirements.
The panel held that Scope 1 and Scope 2 disclosures compel factual information about a company's own operations tied to capital transactions, amounting to commercial speech, and that the state is likely to prevail under intermediate scrutiny, so the November 10, 2026 deadline for 2025 data stands. Scope 3, by contrast, is too loosely tied to a company's own operations to qualify as commercial speech and likely fails strict scrutiny, and SB 261 compels subjective, forward-looking judgments on a politically fraught subject. The panel reversed the district court's denial of a preliminary injunction on those parts and remanded for a determination of whether Scope 3 is severable from the rest of SB 253. Judge Bennett concurred in part and dissented in part, arguing both laws should be enjoined in full.
The ruling is a preliminary-injunction decision, not a final judgment on the merits. The parties have 14 days to seek rehearing or rehearing en banc and may petition the U.S. Supreme Court. The California Air Resources Board (CARB) administers the SB 253 reporting program; GSM reported in October that the rules took effect on October 12 with the first emissions reports due November 10.
(Source: U.S. Court of Appeals for the Ninth Circuit)
来源:美国联邦第九巡回上诉法院
发布:GSM·美国(发布链接)
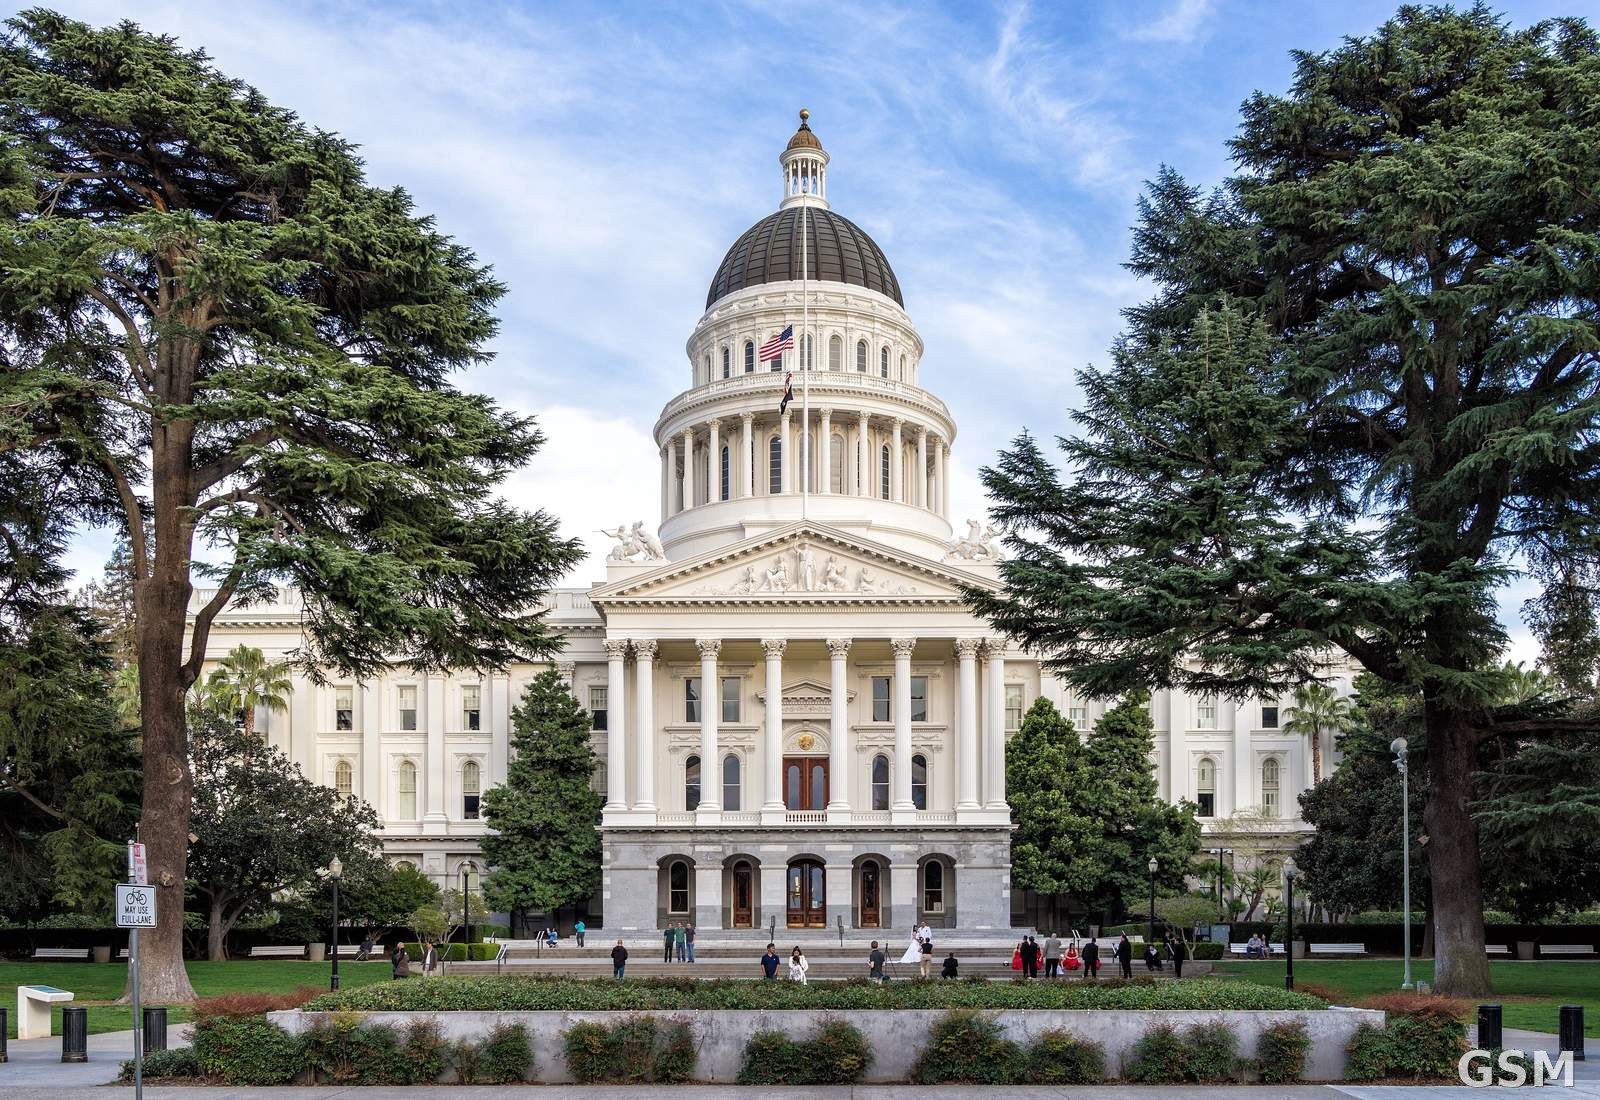
图片来源:图:加州议会大厦(GSM加州固定图库)。 / Photo: California State Capitol (GSM California asset library).
GSM Global · 本篇英文版 English edition of this story