GSM电子书上新:《美国医保入门(一)》开放注册期先看懂计划类型、保费与自付上限
GSM电子书频道推出新系列《美国医保入门》。这套由编辑部综合美国卫生与公众服务部与联邦医保平台 HealthCare.gov 官方公开资料编写的实用指南,第一册赶在开放注册期讲清选计划前要看懂的三个词:计划类型、保费与自付上限。
先说时间。没有雇主医保、需要自己在医保市场购买计划的居民,一般只能在每年11月1日至次年1月15日的开放注册期内投保或更换计划;想让保障从1月1日起生效,通常要在12月15日前完成投保。结婚、生子、失去原有医保等重大生活事件发生后,则有特别注册期可用。
再说计划类型。医保市场计划按自付比例分为铜、银、金、铂四档:铜计划保费最低、看病时自付比例最高,铂计划相反。按就医网络分,HMO计划一般要求在网络内就医并经家庭医生转诊,PPO计划网络外就医也能按一定比例报销,EPO与POS介于其间。高免赔额计划(HDHP)保费较低,并可搭配健康储蓄账户(HSA)存入税前资金支付医疗开支。
最后看两个数字。保费是每月固定要交的钱,免赔额是保险开始分担前自己先付的金额;自付上限则是这一年自己掏钱的封顶数,超过后符合条件的网络内医疗费用由保险全额承担。只比保费高低容易吃亏,把免赔额、共付额与自付上限放在一起算,才知道一个计划一年最贵要花多少钱。符合条件的家庭还可申请保费税收抵免,按收入降低每月保费。
本册适合刚来美国定居的家庭、留学生毕业后离开学校医保者、自雇人士,以及第一次自己买医保的年轻读者。后续各册将依次讲解雇主医保的常见结构、联邦医疗保险(Medicare)的A、B、D部分如何衔接,以及看急诊与住院时如何核对账单。
(来源:美国卫生与公众服务部)
关联:《美国医保入门》电子书
New GSM Ebook: U.S. Health Insurance Basics (Part 1) Covers Plan Types, Premiums and Out-of-Pocket Maximums During Open Enrollment
The GSM Ebooks channel is launching a new series, U.S. Health Insurance Basics, an editorial guide compiled from official publications of the U.S. Department of Health and Human Services and the federal marketplace, HealthCare.gov. Arriving during open enrollment, the first volume explains the three terms to understand before choosing a plan: plan types, premiums and the out-of-pocket maximum.
Start with timing. Residents who do not have employer coverage and buy their own plan through the health insurance marketplace can generally enroll or switch plans only during the annual open enrollment period, from November 1 to January 15, and coverage starting January 1 usually requires enrolling by December 15. Major life events such as marriage, the birth of a child or losing existing coverage open a special enrollment period instead.
Next, plan types. Marketplace plans fall into four metal tiers by cost-sharing: Bronze plans carry the lowest premiums and the highest share of costs at the point of care, and Platinum plans the reverse. By network, HMO plans generally require in-network care with referrals from a primary care doctor, PPO plans reimburse a share of out-of-network care, and EPO and POS plans sit in between. High-deductible health plans (HDHPs) charge lower premiums and can be paired with a health savings account (HSA) funded with pre-tax money for medical expenses.
Finally, look at two numbers together. The premium is the fixed monthly payment, the deductible is what a member pays first before the plan begins to share costs, and the out-of-pocket maximum caps a member's own spending for the year, after which covered in-network care is paid in full by the plan. Comparing premiums alone can be misleading; the deductible, copayments and out-of-pocket maximum together show what a plan can cost in a bad year. Eligible households can also claim the premium tax credit, which lowers monthly premiums based on income.
This volume is written for families newly settled in the United States, graduates leaving school coverage, the self-employed, and younger readers buying their own insurance for the first time. Later volumes will cover how employer plans are usually structured, how Medicare Parts A, B and D fit together, and how to check a bill after an emergency visit or hospital stay.
(Source: U.S. Department of Health and Human Services)
Related: U.S. Health Insurance Basics (GSM Ebook)
来源:美国卫生与公众服务部
发布:GSM·美国(发布链接)
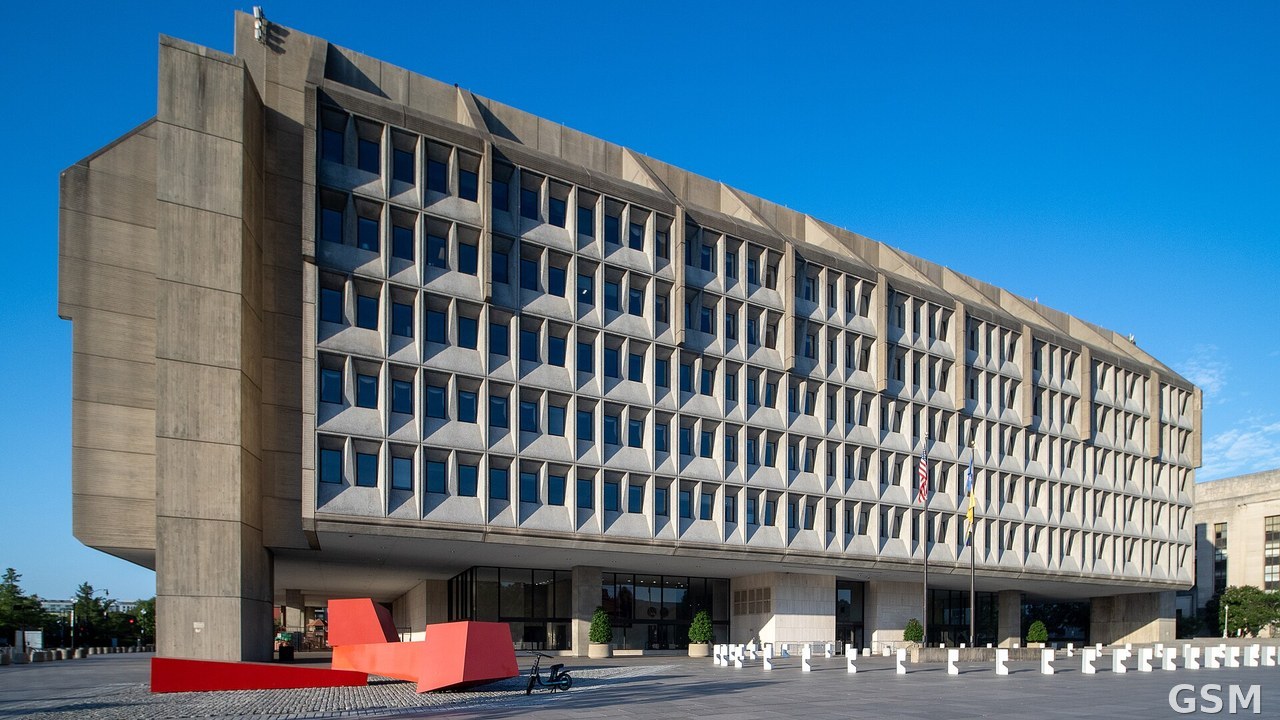
图片来源:图:美国卫生与公众服务部(HHS)总部大楼。GSM固定图库联邦核心包,官方建筑照片。 / Photo: Headquarters building of the U.S. Department of Health and Human Services (HHS). GSM federal core asset pack, official building photo.
GSM Global · 本篇英文版 English edition of this story