12万个账户没核实身份、有人拿风景照开户:FINRA罚Webull 420万美元
美国金融业监管局(FINRA)宣布,对零售券商 Webull Financial LLC 处以420万美元罚款,认定该公司在反洗钱、身份盗窃防范与最佳执行三方面的合规计划未能合理设计,未能跟上业务的快速增长。Webull 在不承认也不否认相关指控的情况下接受处罚结果;除罚款外,该公司还须向 FINRA 证明其反洗钱与身份盗窃防范缺陷已经整改,并聘请一名独立顾问处理其最佳执行计划。
身份核实是此次处罚的核心问题。FINRA 认定,2020年1月至2023年9月间,Webull 每年新开数以百万计的客户账户,期间在通过第三方供应商的身份验证服务开户时,批准了12万多个新账户,却没有形成对这些客户真实身份的合理确信。例如,该公司曾为50多名提交风景照片冒充政府签发身份证件的客户批准开户;在另一些情形中,其自家系统内的信息已经显示客户已经去世,公司仍批准了开户。
在可疑交易监控方面,FINRA 认定 Webull 未能发现并报告多类可疑活动:该公司没有识别或调查473笔未经授权的 ACH 转账,这些转账把其他金融机构客户账户中超过150万美元的资金转入了 Webull 账户;一个账户在开立约18个月内触发了近13,000次潜在操纵交易警报、涉及100多只股票,公司也未能及时调查。此外,该公司缺乏识别潜在可疑价外期权交易的流程,缺乏发现无关联客户使用同一地址或设备交易的监控,也缺乏及时发现欺诈性账户盗用的合理监控。
2020年1月至2023年2月间,Webull 还没有一套合理设计、用以侦测、防范和减轻身份盗窃的计划,而是依赖一套有缺陷的客户识别计划。其后果包括:数十个外国国民账户使用同一 IP 地址或设备开立而未被发现;直到2021年8月,该公司才建立核查多个无关联账户是否使用同一社会安全号码的流程。
在最佳执行方面,FINRA 认定 Webull 未能合理监督最佳执行,也未能对客户的执行质量进行合理、定期而严格的审查。2020年2月至2025年5月间的某些时段,该公司完全没有审查竞争市场中心可提供的执行质量,另一些时候则取得了相关数据却没有充分审查;某些时段占其订单流六至七成的非市价单未被纳入审查,公司也没有按订单类型、逐只证券进行审查。
FINRA 执行副总裁兼执法主管 Bill St. Louis 表示,Webull 的业务增长迅速,但其合规计划没有跟上;公司必须确保其监管体系随业务增长而扩展、并应对业务带来的风险,Webull 在核实客户身份、侦测可疑活动和确保客户交易获得最佳执行这些根本环节上都没有做到,FINRA 会在公司的合规计划不足以应对其业务风险时追究责任。
这不是 Webull 第一次被 FINRA 罚款。2025年,FINRA 曾对该公司处以160万美元罚款,理由是其未能合理监督和留存在社交媒体上有大量粉丝的推广者(即所谓网红)为公司所作的宣传通讯,其中包括不公平、不平衡,或带有承诺性、夸大性的表述。(来源:美国金融业监管局)
FINRA Fines Webull $4.2 Million: 120,000 Accounts Approved Without Verified Identities, Some Opened With Landscape Photos
The Financial Industry Regulatory Authority (FINRA) has fined retail brokerage Webull Financial LLC $4.2 million, finding that the firm failed to implement reasonably designed programs for anti-money laundering, identity theft prevention and best execution as its business grew rapidly. In settling the matter, Webull consented to the entry of FINRA's findings without admitting or denying the charges. In addition to the fine, the firm agreed to certify remediation of the deficiencies in its anti-money laundering and identity theft prevention programs and to retain an independent consultant to address its best execution program.
Identity verification is at the center of the action. FINRA found that between January 2020 and September 2023, while Webull was opening millions of new customer accounts each year, the firm approved the opening of more than 120,000 new customer accounts using identity verification services provided by its third-party vendors without forming a reasonable belief that it knew the true identity of those customers. For example, the firm approved accounts for more than 50 customers who submitted photos of scenic landscapes instead of government-issued identification, and in other instances it approved accounts for customers despite information in its own systems indicating that the customers were deceased.
On suspicious activity monitoring, FINRA found that Webull failed to detect and report a variety of suspicious transactions. The firm failed to identify or investigate 473 unauthorized ACH transfers used to move over $1.5 million from customers at other financial institutions into Webull accounts, and it failed to timely investigate a single account that triggered nearly 13,000 alerts for potentially manipulative trading activity in more than 100 stock symbols during the approximately 18 months the account was open. The firm also had no processes to identify potentially suspicious out-of-the-money options trading, lacked surveillance to identify unrelated customers trading from the same address or device, and lacked reasonable surveillance to detect fraudulent account takeovers in a timely manner.
Between January 2020 and February 2023, Webull also failed to have an identity theft prevention program reasonably designed to detect, prevent and mitigate identity theft, relying instead on a deficient customer identification program. As a result, the firm failed to detect red flags including dozens of accounts opened for foreign nationals using the same IP address or device, and it did not implement a process to check whether multiple unrelated accounts were opened using the same Social Security number until August 2021.
On best execution, FINRA found that Webull failed to reasonably supervise for best execution and failed to conduct reasonable, regular and rigorous reviews of customers' execution quality. At certain points between at least February 2020 and at least May 2025, the firm conducted no review of the execution quality available at competing market centers, and at other times it obtained such data but failed to sufficiently review it. At certain points it also failed to review execution quality for non-marketable orders, which made up 60 to 70 percent of its order flow during certain periods, and did not conduct reviews on a type-of-order or security-by-security basis as required.
Bill St. Louis, FINRA's Executive Vice President and Head of Enforcement, said Webull's business grew rapidly but its compliance program did not keep pace, and that firms must ensure their supervisory systems grow with their business and address the risks they present. He said Webull failed to do so in fundamental areas, including verifying customers' identities, detecting suspicious activity and ensuring the best possible execution of customer trades, and that FINRA holds firms accountable when their compliance programs do not adequately address the risks created by their business.
It is not Webull's first FINRA fine. In 2025, FINRA censured and fined the firm $1.6 million for failing to reasonably supervise and retain social media communications by influencers who promoted the firm, including statements that were not fair and balanced, or were promissory or exaggerated. (Source: Financial Industry Regulatory Authority)
来源:美国金融业监管局
发布:GSM·美国(发布链接)
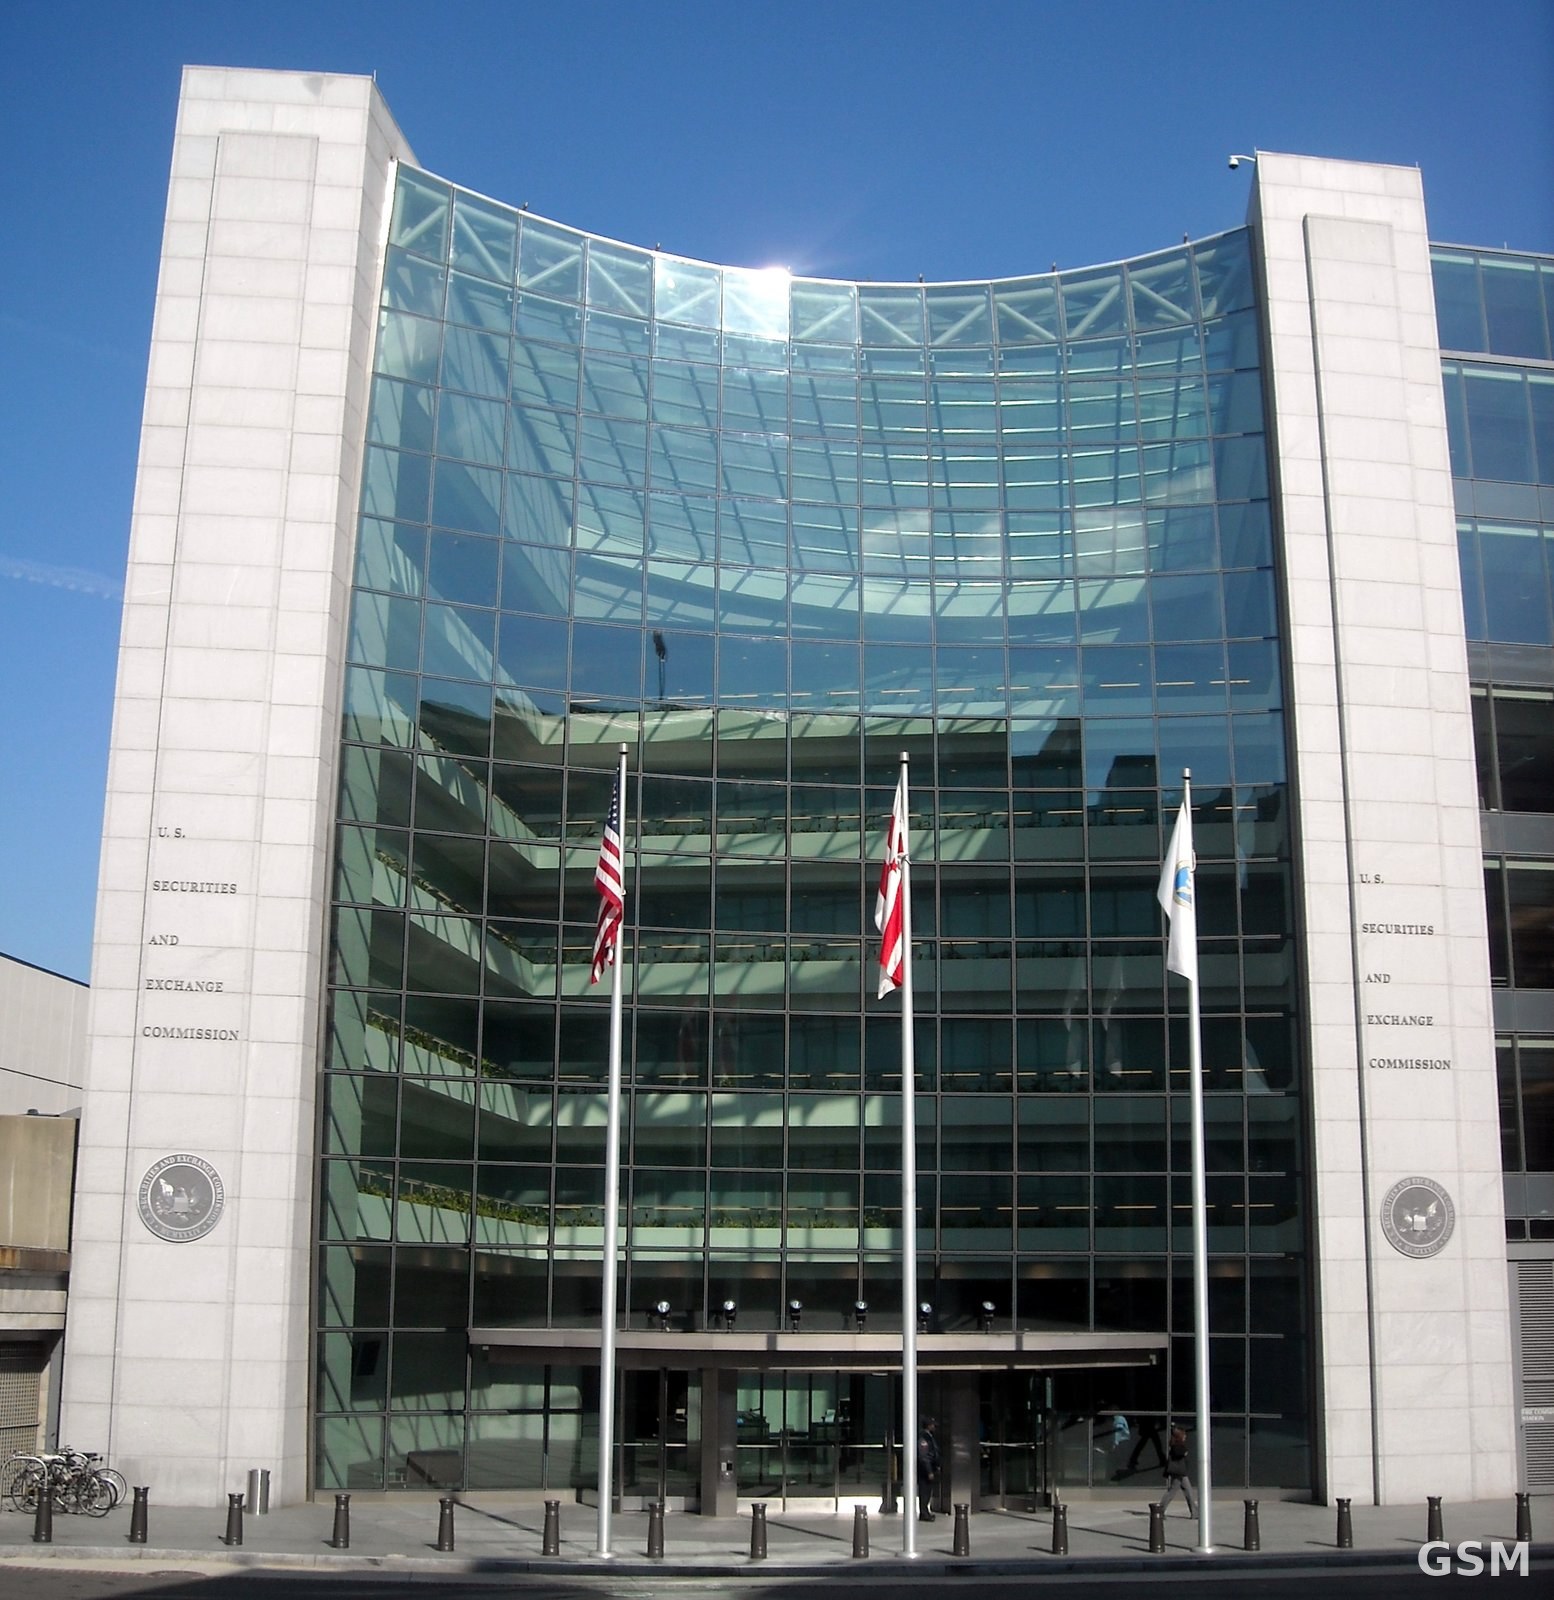
图片来源:图:美国证券交易委员会(SEC)总部大楼,FINRA 受 SEC 监管。AgnosticPreachersKid 摄,CC BY-SA 3.0,经 Wikimedia Commons。 / Photo: U.S. Securities and Exchange Commission headquarters; FINRA is overseen by the SEC. By AgnosticPreachersKid, CC BY-SA 3.0, via Wikimedia Commons.
GSM Global · 本篇英文版 English edition of this story