国税局 IRS 与财政部部分撤回2016年免税分拆拟规:废止「当然构成规避工具」测试与两项反滥用规则
华盛顿——财政部与国税局(IRS)10月21日在《联邦公报》刊登通知,部分撤回两部门2016年就《国内税收法》第355条免税分拆交易提出的拟议法规(REG-134016-15),废止其中三项已悬置十年的内容。
被撤回的包括:一项「当然」(per se)测试——按原拟规,若分拆后任一公司持有的非经营性资产占比过高,该交易即被直接认定为股东套取公司收益的「工具」(device),而不论是否存在真实商业目的等其他因素;以及两项与该测试和「积极经营业务」最低门槛挂钩的反滥用规则。通知说明,撤回不影响其他规则与司法原则的适用,包括「实质重于形式」与「分步交易」原则;财政部与国税局表示将继续研究2016年拟规涉及的相关问题。
2016年拟规的其余部分未被撤回,仍然有效待议,其中包括以20%为界的非经营性资产考量因素、商业目的因素的收窄,以及分拆双方「积极经营业务」资产占比至少5%的最低要求。据彭博税务(Bloomberg Tax)等专业媒体报道,两部门此次是因利益相关方对上述规则普遍持批评意见而作出撤回;规划分拆交易的公司因此少了一道拟议中的硬性门槛,但交易文件中的商业目的论证仍是审查重点。
IRS and Treasury Partially Withdraw 2016 Proposed Rules on Tax-Free Spin-Offs, Dropping the Per Se Device Test and Two Anti-Abuse Rules
Washington — The Treasury Department and the Internal Revenue Service (IRS) on October 21 published a notice in the Federal Register partially withdrawing their 2016 proposed regulations under Section 355 of the Internal Revenue Code on tax-free spin-off transactions (REG-134016-15), shelving three elements that had been pending for a decade.
Withdrawn are a 'per se' device test — under which a distribution could have been treated as a device to extract corporate earnings solely because either company held too large a share of nonbusiness assets, regardless of a genuine business purpose — and two related anti-abuse rules tied to that test and to the minimum active-trade-or-business requirement. The notice states that the withdrawal does not affect the potential application of other rules or judicial doctrines, such as the substance-over-form and step-transaction doctrines, and that Treasury and the IRS continue to study the issues addressed in the 2016 proposals.
Other parts of the 2016 proposals remain outstanding, including the 20 percent nonbusiness-asset consideration, a narrower business-purpose factor and a requirement that at least 5 percent of each company's assets satisfy the active trade or business test. According to Bloomberg Tax and other professional outlets, the agencies withdrew the rules after stakeholders were generally critical of them. Companies planning spin-offs therefore face one less proposed hard threshold, though a well-documented business purpose remains central to review.
发布:GSM·美国(发布链接)
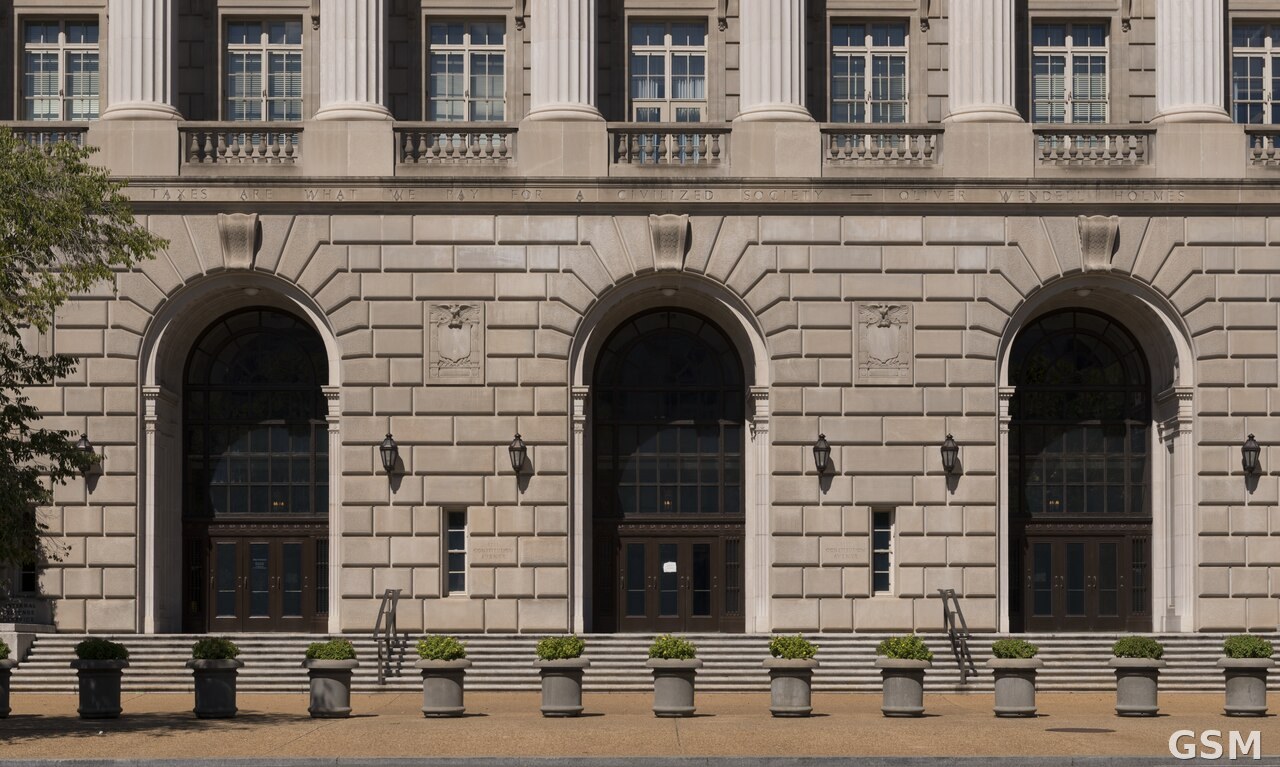
图片来源:图:位于华盛顿 Federal Triangle 的国税局 IRS 总部大楼。照片:Carol M. Highsmith,公有领域,经Wikimedia Commons。The Internal Revenue Service headquarters building in the Federal Triangle, Washington. Photo: Carol M. Highsmith, public domain, via Wikimedia Commons.
GSM Global · 本篇英文版 English edition of this story