美国家庭债务三季度增至19.1万亿美元 逾期率升至5.0%
纽约联邦储备银行11月10日发布2026年第三季度《家庭债务与信用报告》。报告显示,美国家庭债务总额当季增加3,340亿美元,增幅1.8%,达到19.1万亿美元;处于某种逾期状态的债务占未偿债务的5.0%,比上一季度上升0.3个百分点。报告数据来自纽约联储消费者信用小组,该样本取自 Equifax 的匿名信用报告,覆盖全美家庭。
住房类债务是当季增量的主体。抵押贷款余额增加2,570亿美元,9月底达到13.4万亿美元,当季新发放的抵押贷款达5,950亿美元,发放速度明显加快。房屋净值信用额度余额增加230亿美元,达到4,810亿美元,是2005年以来最大的单季增幅,这类额度的上限当季再增310亿美元,延续了2022年开始的扩张。
其他债务同步温和增长。信用卡余额增加220亿美元,达到1.29万亿美元,信用卡总额度当季增加1,150亿美元。汽车贷款余额增加210亿美元,达到1.73万亿美元,当季新发放汽车贷款2,080亿美元。学生贷款余额小幅增加50亿美元,达到1.66万亿美元。与去年同期相比,美国家庭债务总额多出5,200亿美元。
逾期结构出现分化。转入早期逾期的比例在汽车贷款与抵押贷款上继续小幅上升,信用卡则略有改善。转入严重逾期,也就是逾期90天以上的比例,信用卡与学生贷款略有改善,汽车贷款与房屋净值信用额度基本持平,抵押贷款有所上升,年化比例由去年同期的1.28%升至1.60%,但报告指出,这一水平按历史标准仍属低位。
纽约联储经济研究顾问 Donghoon Lee 表示,家庭债务温和上升,主要由抵押贷款与房屋净值信用额度的发放带动;住房类债务的逾期转换率虽然有所爬升,这类贷款的整体信用质量仍然强健。这份报告按季度发布,本次数据截至2026年9月底。
US Household Debt Rose to $19.1 Trillion in the Third Quarter as the Delinquency Rate Climbed to 5.0%
The Federal Reserve Bank of New York issued its Quarterly Report on Household Debt and Credit for the third quarter of 2026 on November 10. Total household debt expanded by $334 billion, a 1.8 percent increase, to reach $19.1 trillion, while 5.0 percent of outstanding debt was in some stage of delinquency, up 0.3 percentage points from the previous quarter. The report is based on the New York Fed's Consumer Credit Panel, a nationally representative sample drawn from anonymized Equifax credit data.
Housing debt accounted for most of the quarterly increase. Mortgage balances rose by $257 billion and totaled $13.4 trillion at the end of September, with $595 billion in newly originated mortgages appearing in the quarter, a notable pickup in origination pace. Home equity line of credit balances rose by $23 billion to $481 billion, the largest quarterly increase observed since 2005, and HELOC limits rose by another $31 billion, continuing an expansion that began in 2022.
Other borrowing grew moderately. Credit card balances rose by $22 billion to $1.29 trillion, and aggregate credit card limits rose by $115 billion. Auto loan balances increased by $21 billion to $1.73 trillion, with $208 billion in new auto loans originated during the quarter. Student loan balances edged up by $5 billion to $1.66 trillion. Total household debt stood $520 billion higher than a year earlier.
Delinquency patterns diverged by loan type. Transition into early delinquency continued to tick up for auto loans and mortgages but improved slightly for credit cards. Transition into serious delinquency, defined as 90 days or more past due, slightly improved for credit cards and student loans, remained flat for auto loans and home equity lines, and worsened for mortgages, with the annualized flow rising to 1.60 percent from 1.28 percent a year earlier, a level the report notes remains low by historical standards.
"Household debt levels rose moderately, led by increases in mortgage and home equity line of credit originations," said Donghoon Lee, Economic Research Advisor at the New York Fed. "Although delinquency transition rates for housing debts have crept up, the overall credit quality of these loans remains strong." The quarterly report reflects data through the end of September 2026.
来源:纽约联邦储备银行
发布:GSM·美国(发布链接)
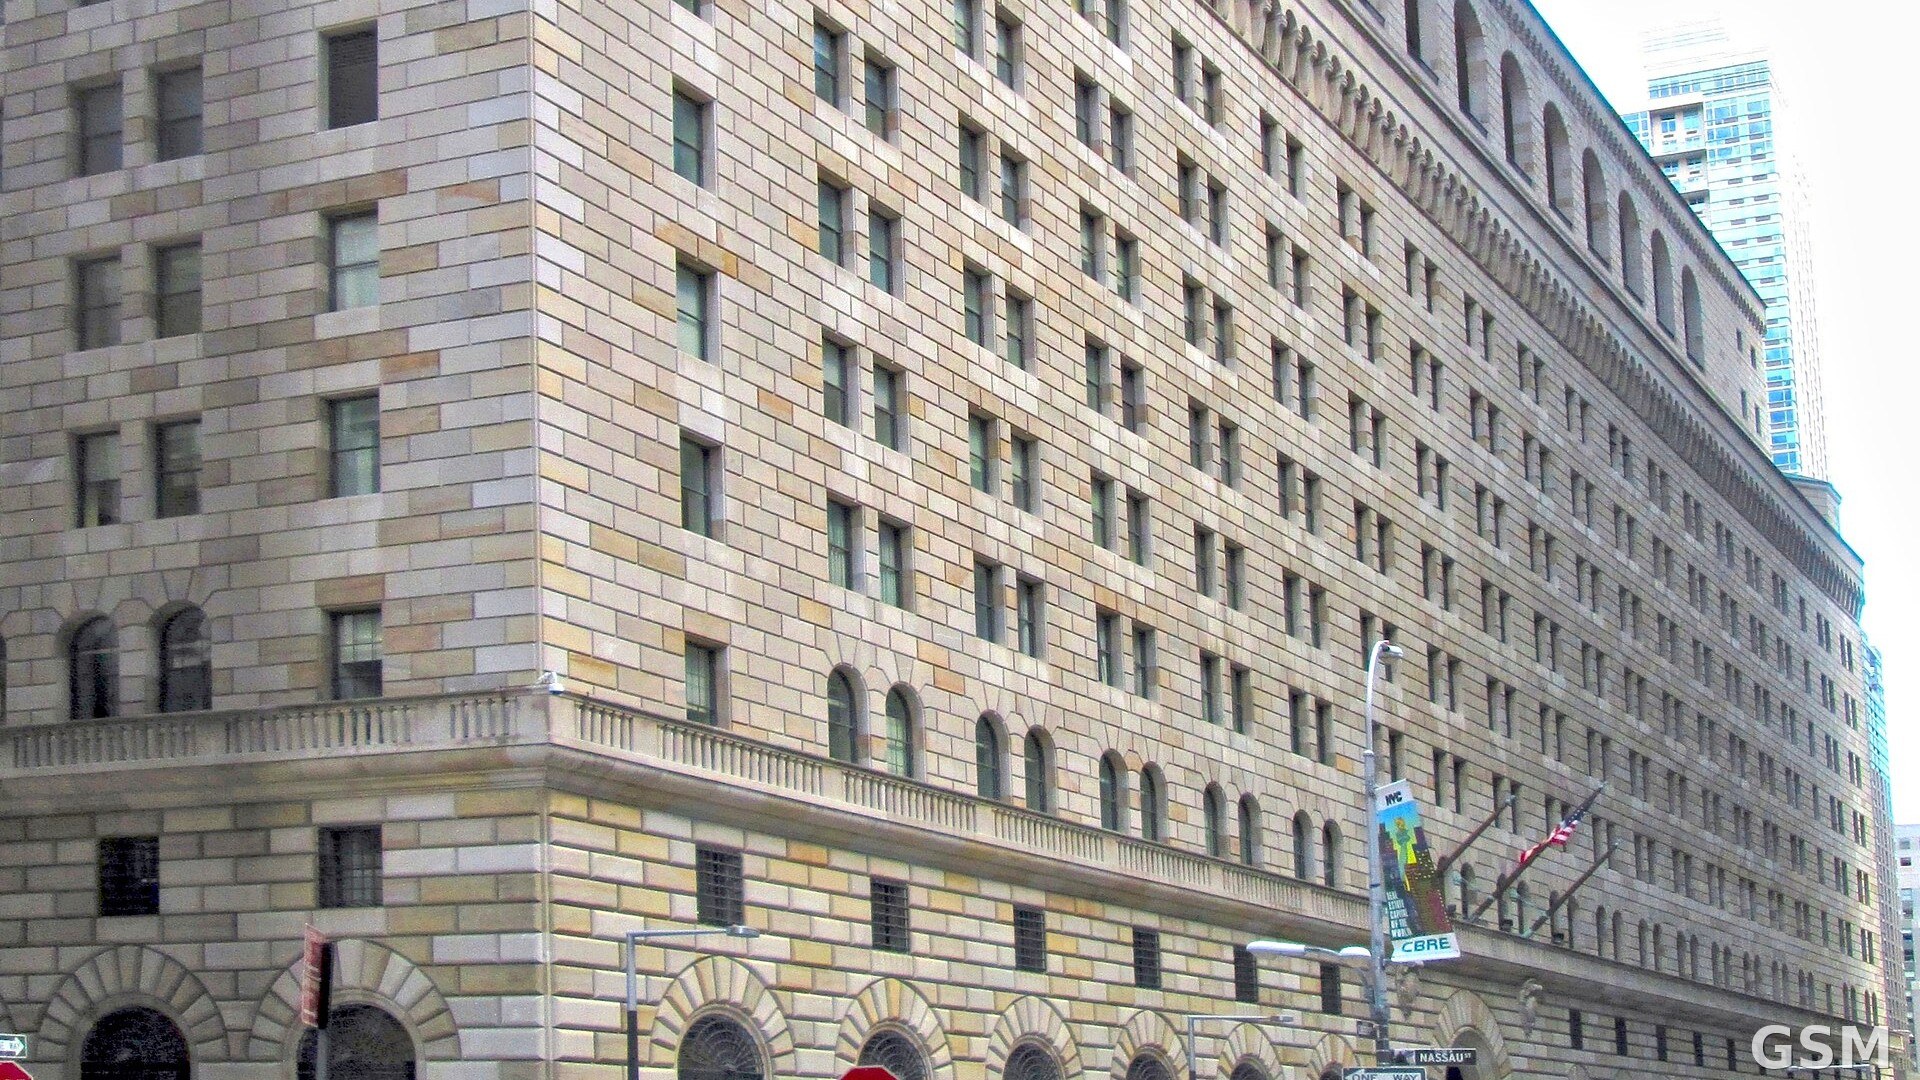
图片来源:图:纽约联邦储备银行总部大楼(33 Liberty Street)。Beyond My Ken 摄,CC BY-SA 4.0,Wikimedia Commons。 / Photo: Federal Reserve Bank of New York headquarters, 33 Liberty Street. By Beyond My Ken, CC BY-SA 4.0, via Wikimedia Commons.
GSM Global · 本篇英文版 English edition of this story