美国住房与学区房:好学校旁边的房子
一、学区线,也是一条价格线
在德州 Southlake,Carroll 独立学区内房子的中位价是 216 万美元。走出学区边界,同一都市区的房价中位是 439,967 美元。差价 391%(Realtor.com)。这条线画在地图上是学区边界,画在房价上,是一道 170 多万美元的坎。
好学校旁边的房子,一直是美国房市里最贵的那一类。Realtor.com 2016 年的一项研究写道:GreatSchools 评分 9 至 10 分的学区,房价平均 40 万美元,比当时全美中位价 26.9 万美元高 49%,比同一区域低评分学区的 22.5 万美元高 77%。好学区的房子售出快 8 天,浏览量高 26%。
二、全国房价:涨了六年
全美现房中位价,2026 年 9 月为 417,500 美元,同比上涨 1.3%,是 9 月份的历史最高,也是连续第 39 个月同比上涨(NAR)。2019 年中位价 274,600 美元,七年累计上涨约 52%。房价收入比 2024 年为 5.1 倍,是有记录以来最高:2019 至 2024 年,中位房价涨 48%,中位家庭收入只涨 17%。按 20% 首付计,买一套中位价房所需的年收入,2019 年约 51,000 美元,2024 年约 96,000 美元。
S&P Cotality Case-Shiller 全美指数 2026 年 8 月同比上涨 2.1%,但扣除通胀后,房价已连续 15 个月下跌—名义价格还在涨,实际购买力在缩水。
抵押贷款利率:Freddie Mac 调查,30 年固定利率截至 2026 年 11 月 5 日当周为 7.18%。2026 年 2 月 26 日曾跌至 5.98%,是三年半来首次低于 6%。历史最高是 1981 年 10 月的 18.63%,历史最低是 2021 年 1 月的 2.65%。
三、一分值多少钱
2026 年 10 月发表在 Emerald《International Journal of Housing Markets and Analysis》上的一项研究,用大休斯敦地区 2,332 套独栋挂牌样本算了一笔账:GreatSchools 评分每高 1 分,挂牌价高 4.57%,按样本中位价 344,082 美元计,约合 15,733 美元。评分与价格呈线性关系。
同一项研究还发现,德州教育局的官方评分在联合回归中并不显著—市场更认 GreatSchools 的评分,而不是州政府的官方评分。
极端个案写在 Realtor.com 的榜单上:加州 Beverly Hills 联合学区溢价 689%(380 万美元对洛杉矶县 55 万美元);德州 Highland Park 溢价 632%(180 万美元对达拉斯县 27.7 万美元)。
四、为什么贵:房产税那条链
美国公立中小学的经费,高度依赖地方房产税。NCES 数据(2022–23 学年):房产税占全美公立中小学经费的 33.2%,是单一最大税源;房产税约占地方学校收入的 83%。经费结构是州政府 45.1%、地方 42.0%、联邦 12.9%,公立中小学总经费 9,818 亿美元。
这是制度性事实,不是因果断言:房价高的学区,房产税基大,地方学校经费相应充裕。学区、房价与学校经费,就这样连成一条链。
五、买房的人:40 岁才第一次买房
NAR《2026 Profile of Home Buyers and Sellers》(2026 年 11 月 5 日发布,交易期 2025 年 7 月至 2026 年 6 月)写道:首次购房者占 22%,中位年龄 40 岁,仍为历史最高。创纪录的 10% 首次购房者全款购房,其中 28% 用遗产支付(贷款购房者中仅 9% 用遗产);全款首次购房者中位年龄 54 岁,贷款者 38 岁。
典型入门房(挂牌价低于 35 万美元的房源),2026 年 6 月挂牌价 344,000 美元,2019 年 6 月为 256,000 美元;买家需家庭年收入约 78,000 美元,2019 年为 43,000 美元,涨逾 80%(Realtor.com)。
NAR 首席经济学家办公室估算:40 岁而非 30 岁置业,典型入门房一生少约 150,000 美元净值。这是 NAR 的估算,不是房价预测。
供应方面,Realtor.com《2026 Housing Supply Gap Report》称 2025 年缺口 4.03M 套(2024 年为 3.8M 套);1.82M 千禧一代与 Z 世代因负担不起而未独立成家的「缺失」家庭,为四年最高。
六、持有成本:税与保险
房产税各州差异极大。Tax Foundation 2026 年表(2024 年 ACS 数据):最高的新泽西与伊利诺伊均为 1.88%,最低的夏威夷为 0.29%。全美房主中位缴税 3,211 美元。一套 40 万美元的房子,新泽西年缴 7,520 美元,夏威夷 1,160 美元,年差 6,360 美元。州和地方税(SALT)扣除上限 2025 年从 10,000 美元提至 40,000 美元,2030 年恢复至 10,000 美元。
保险也在涨。Insurify《2026 Insuring the American Homeowner Report》:全美平均年保费 2025 年底为 2,948 美元,2025 年涨 12%,预计 2026 年底为 3,057 美元,连续第五年上涨,自 2021 年以来累计涨 46%。佛罗里达最贵,2025 年底 8,292 美元;加州 2025 年底 2,455 美元,预计 2026 年为 2,843 美元,涨 16%,为各州最大涨幅,与 2025 年 1 月 Palisades 与 Eaton 野火损失有关。
七、搬家的人:加州走,德州来
人口普查局 Vintage 2025 估计(2024 年 7 月 1 日至 2025 年 7 月 1 日):加州国内净迁移 −229,077 人,全国垫底;德州 +67,299 人,全国第二。ACS 2024:加州迁往德州 77,161 人,为全美最大单条州际流向;加州 2024 年迁出 661,205 人,全国最多。
租金也在分化。Zillow 租金指数 2026 年 9 月典型市场租金 1,932 美元/月,同比上涨 2.7%。Zillow 2026 年 10 月 7 日的一项研究写道:年收入 100,000 美元的租房者,在 San Jose 中位可负担房仅 650 平方英尺、一居一卫,95% 为公寓或共管;在孟菲斯可租 2,100 平方英尺独栋。
八、华人视角:数字里的位置
华人集中地区的房价(Zillow ZHVI,2026 年 9 月):加州典型房价 761,538 美元,同比上涨 0.6%;新泽西 575,123 美元,上涨 4.0%;德州 296,424 美元,下跌 1.4%。全美典型房价 368,697 美元(2026 年 8 月)。ZHVI 为全部房源估值,与 NAR 现房成交中位价口径不同。
人口普查局 CPS/HVS 季度调查:2026 年第三季度,亚裔、夏威夷原住民与太平洋岛民(ANHPI)自有住房率 62.3%,全美为 65.5%。人口普查局《Wealth of Households: 2024》(2026 年 7 月发布):近 29% 的亚裔家庭净资产在 100 万美元以上,为 2024 年全美最富裕族群;但亚裔家庭自有住房率(SIPP 口径 58.5%)低于非西语裔白人家庭(70.2%),直接持有股票或共同基金的比例为 46.3%。
需要明说的是:在美华人家庭购房偏好、学区房交易特点的系统性公开数据,本次未查到,本文不写这类说法。
九、收束:回到 Southlake
回到德州 Southlake。Carroll 独立学区内房子的中位价仍是 216 万美元,学区外仍是 439,967 美元。学区线画在地图上,价格线画在同一处。好学校旁边的房子,贵的是房子,标价的是学区。
Housing and School-District Homes: The House Next to a Good School
1. The district line is also a price line
In Southlake, Texas, the median home price inside the Carroll Independent School District is $2.16 million. Step outside the district boundary, and the median price in the same metropolitan area is $439,967. The difference is 391% (Realtor.com). Drawn on a map, that line is a school district boundary; drawn on home prices, it is a gap of more than $1.7 million.
Homes next to good schools have long been among the most expensive in the American housing market. A 2016 Realtor.com study found that homes in districts rated 9 to 10 by GreatSchools averaged $400,000 — 49% above the national median of $269,000 at the time, and 77% above homes in low-rated districts in the same area ($225,000). Homes in good districts sold eight days faster and drew 26% more views.
2. National prices: six years of increases
The national median existing-home price was $417,500 in September 2026, up 1.3% year over year — a record for September and the 39th consecutive month of year-over-year gains (National Association of Realtors). The 2019 median was $274,600; over seven years, prices rose about 52%. The price-to-income ratio reached 5.1 in 2024, the highest on record: from 2019 to 2024, the median home price rose 48% while median household income rose only 17%. With a 20% down payment, the annual income needed to buy a median-priced home was about $51,000 in 2019 and about $96,000 in 2024.
The S&P Cotality Case-Shiller National Index rose 2.1% year over year in August 2026, but after adjusting for inflation, home prices have now fallen for 15 consecutive months — nominal prices are still rising while real purchasing power shrinks.
Mortgage rates: the Freddie Mac survey put the 30-year fixed rate at 7.18% in the week ending November 5, 2026. It fell to 5.98% on February 26, 2026, the first reading below 6% in three and a half years. The historical high was 18.63% in October 1981; the historical low was 2.65% in January 2021.
3. What one point is worth
A study published in October 2026 in Emerald's International Journal of Housing Markets and Analysis put a number on it. Using 2,332 single-family listings in the Greater Houston area, the authors found that each additional GreatSchools point was associated with a 4.57% higher list price — about $15,733 at the sample median price of $344,082. The relationship between rating and price was linear.
The same study found that the Texas Education Agency's official rating was not significant in the joint regression — the market trusts the GreatSchools rating, not the state government's official rating.
The extreme cases are on Realtor.com's list: the Beverly Hills Unified School District in California carries a 689% premium ($3.8 million versus $550,000 in Los Angeles County); Highland Park in Texas carries a 632% premium ($1.8 million versus $277,000 in Dallas County).
4. Why it costs more: the property-tax chain
Funding for American public schools depends heavily on local property taxes. According to National Center for Education Statistics data for the 2022–23 school year, property taxes accounted for 33.2% of all public elementary and secondary school funding — the single largest tax source — and about 83% of local school revenue. The funding mix was 45.1% from state governments, 42.0% from local sources, and 12.9% from the federal government, for total public school funding of $981.8 billion.
That is an institutional fact, not a causal claim: districts with higher home prices have a larger property-tax base, and local school funding is correspondingly larger. District, home price, and school funding are linked in a single chain.
5. The buyers: first homes at age 40
The National Association of Realtors' 2026 Profile of Home Buyers and Sellers (published November 5, 2026, covering transactions from July 2025 through June 2026) reports that first-time buyers made up 22% of buyers, with a median age of 40 — still the highest on record. A record 10% of first-time buyers paid all cash, and 28% of those paid with an inheritance (against 9% of buyers who took out a mortgage); the median age of all-cash first-time buyers was 54, against 38 for buyers with a mortgage.
A typical starter home (listings priced below $350,000) listed at $344,000 in June 2026, against $256,000 in June 2019; buyers needed household income of about $78,000, against $43,000 in 2019 — an increase of more than 80% (Realtor.com).
The NAR chief economist's office estimates that buying at 40 rather than 30 costs a typical starter-home buyer about $150,000 in lifetime equity. That is an NAR estimate, not a price forecast.
On supply, Realtor.com's 2026 Housing Supply Gap Report put the 2025 gap at 4.03 million homes (3.8 million in 2024); 1.82 million millennial and Generation Z "missing households" — young adults who have not formed independent households because they cannot afford to — the highest in four years.
6. The cost of holding: taxes and insurance
Property taxes vary enormously by state. The Tax Foundation's 2026 table (based on 2024 American Community Survey data) puts New Jersey and Illinois highest at 1.88% each, and Hawaii lowest at 0.29%. The median American homeowner pays $3,211 a year. On a $400,000 home, New Jersey charges $7,520 a year against Hawaii's $1,160 — a difference of $6,360 a year. The state and local tax (SALT) deduction cap rose from $10,000 to $40,000 in 2025 and returns to $10,000 in 2030.
Insurance is rising too. Insurify's 2026 Insuring the American Homeowner Report puts the national average annual premium at $2,948 at the end of 2025, up 12% in 2025 and expected to reach $3,057 by the end of 2026 — a fifth consecutive annual increase and a cumulative 46% rise since 2021. Florida is the most expensive, at $8,292 at the end of 2025; California stood at $2,455 at the end of 2025 and is expected to reach $2,843 in 2026, up 16% — the largest increase of any state, linked to losses from the January 2025 Palisades and Eaton wildfires.
7. The movers: out of California, into Texas
The Census Bureau's Vintage 2025 estimates (July 1, 2024 to July 1, 2025) show California with domestic net migration of −229,077 people, the lowest in the nation, and Texas at +67,299, the second highest. The 2024 American Community Survey counted 77,161 people moving from California to Texas, the largest single interstate flow in the country; California saw 661,205 people leave in 2024, the most of any state.
Rents are diverging too. The Zillow Observed Rent Index put the typical market rent at $1,932 a month in September 2026, up 2.7% year over year. A Zillow study published October 7, 2026, found that a renter earning $100,000 a year could afford a median home of only 650 square feet — one bedroom, one bathroom, 95% apartments or condominiums — in San Jose, but a 2,100-square-foot detached house in Memphis.
8. The Chinese American view: where the numbers sit
Home prices in areas with large Chinese populations (Zillow Home Value Index, September 2026): California's typical home value was $761,538, up 0.6% year over year; New Jersey's was $575,123, up 4.0%; Texas's was $296,424, down 1.4%. The national typical value was $368,697 (August 2026). The ZHVI covers all homes, including those not for sale, and is measured differently from the NAR existing-home median.
The Census Bureau's Current Population Survey/Housing Vacancies Survey put the homeownership rate for Asian, Native Hawaiian, and Pacific Islander (ANHPI) households at 62.3% in the third quarter of 2026, against 65.5% nationally. The Census Bureau's Wealth of Households: 2024 (published July 2026) found that nearly 29% of Asian households had net worth of $1 million or more — the wealthiest group in the country in 2024 — but that Asian homeownership (58.5% on the Survey of Income and Program Participation measure) was below that of non-Hispanic white households (70.2%), while 46.3% of Asian households held stocks or mutual funds directly.
It must be stated plainly: no systematic public data were found on home-buying preferences or school-district purchasing patterns among Chinese families in the United States, and this article makes no such claims.
9. Close: back to Southlake
Back in Southlake, Texas. The median home inside the Carroll Independent School District is still $2.16 million; outside the district it is still $439,967. The district line is drawn on the map; the price line is drawn in the same place. The house next to a good school is expensive; what the price tags is the district.
来源:全美房地产经纪人协会等机构数据
发布:GSM·美国(发布链接)
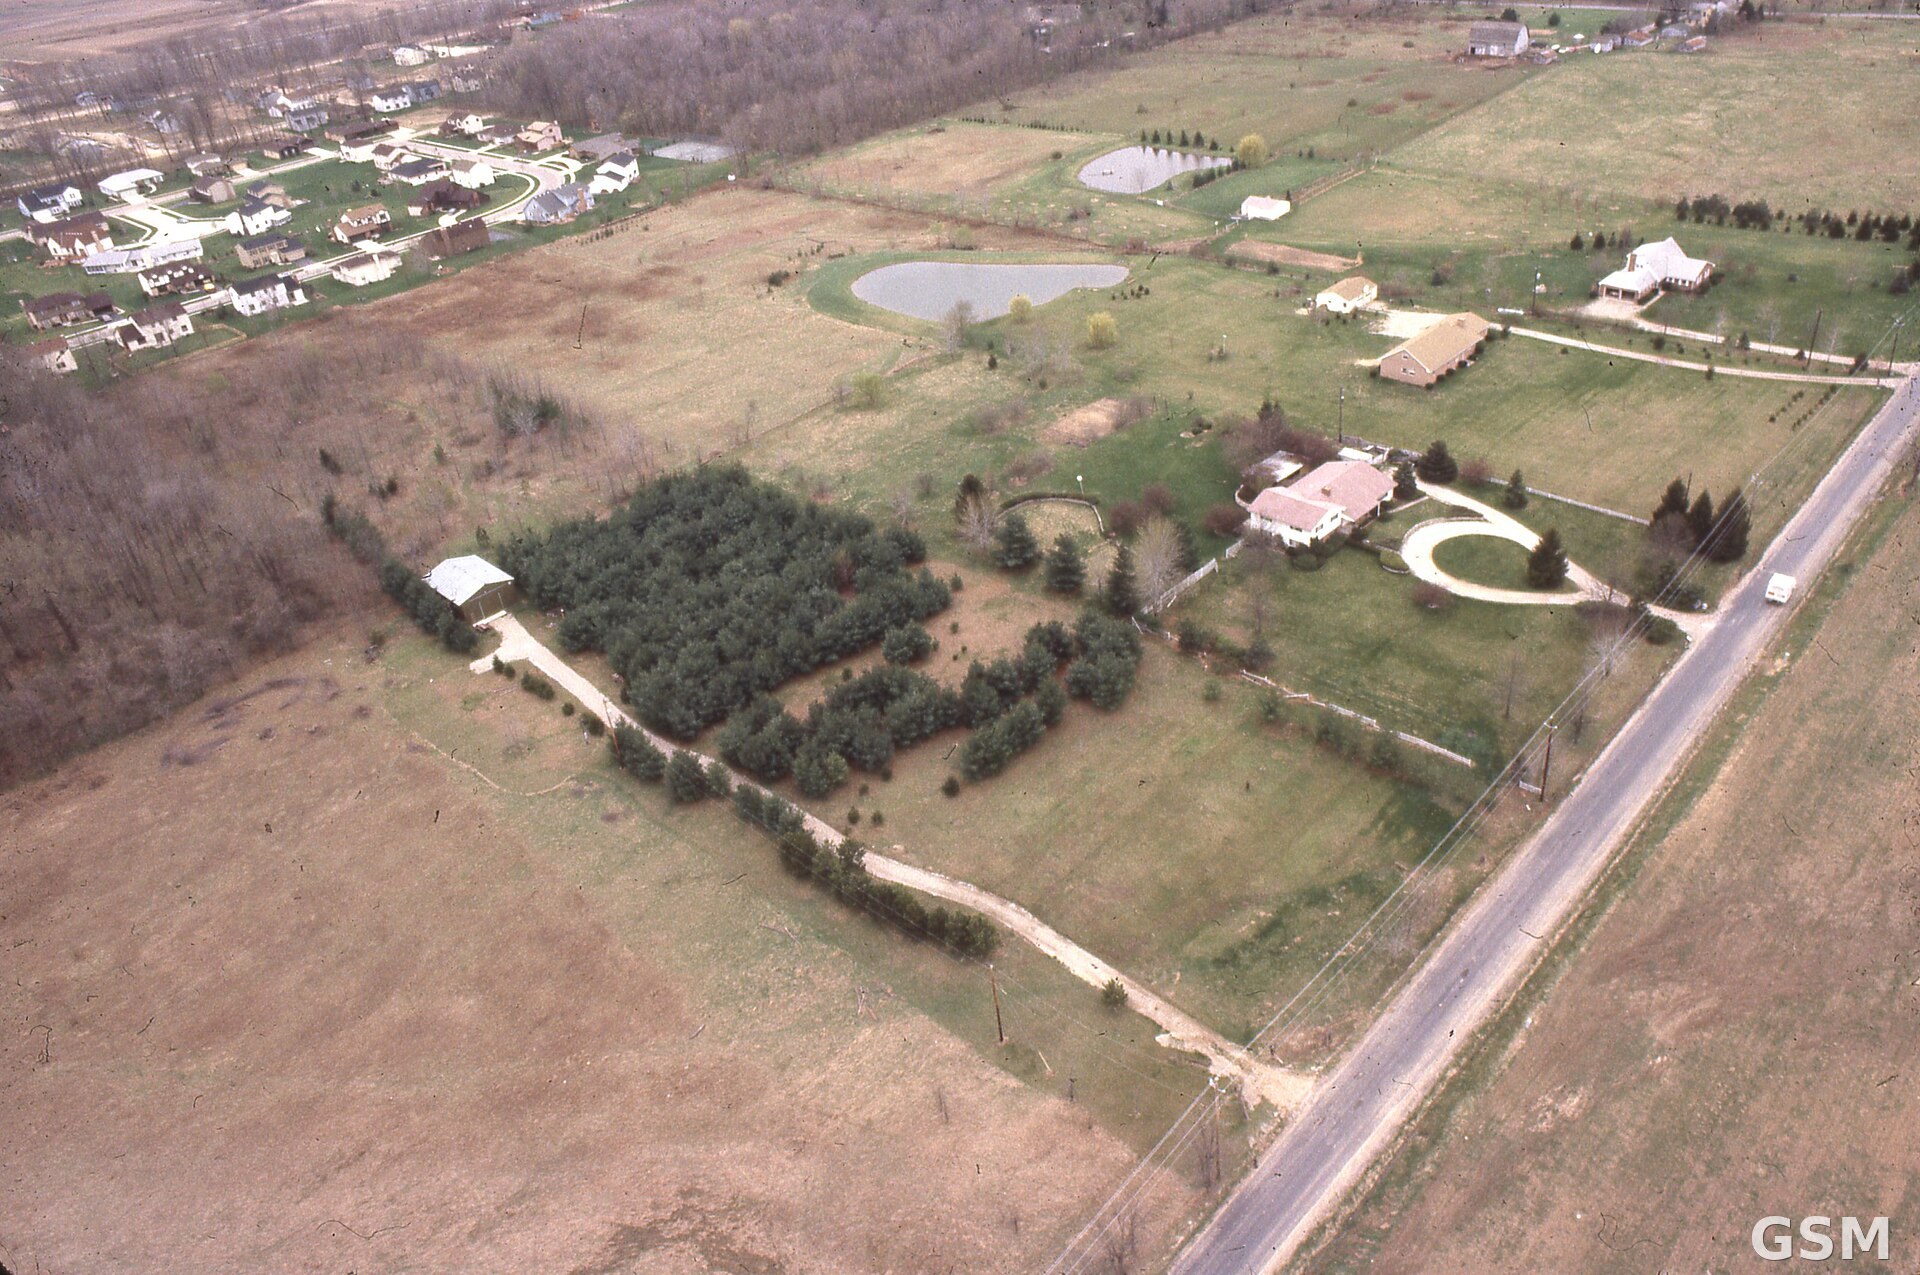
图片来源:图:美国郊区住宅区航拍。Wikimedia Commons,公共领域。 / Photo: Aerial view of a U.S. suburban residential neighborhood. Wikimedia Commons, public domain.
GSM Global · 本篇英文版 English edition of this story