Preferred Bank 三季度净利3,290万美元:不良贷款利息冲回拖累净利息收入,存款环比增长1.2%
总部位于加州洛杉矶(Los Angeles)的 Preferred Bank(NASDAQ: PFBC)10月23日公布截至2026年9月30日的第三季度业绩:当季净利3,290万美元、摊薄每股收益2.73美元,较上年同期减少300万美元、较第二季度减少59.2万美元。该行是加州较大的独立商业银行之一,最初以华人银行起家,如今客户以多元主流市场为主,在 Alhambra、City of Industry、Irvine、Diamond Bar 等华人聚居城市设有分行。
盈利方面,当季净利息收入6,670万美元,同比减少460万美元、环比减少330万美元;净息差3.49%,低于第二季度的3.73%与上年同期的3.92%。该行表示,主因是当季将一笔5,670万美元贷款列入不良状态、另有四笔合计1,350万美元,由此冲回利息收入210万美元,而第二季度曾有290万美元利息回收;此外其次级债自6月16日起由固定利率转为浮动利率(三个月 SOFR 加278个基点),第三季度票息升至6.44%,推高利息支出。非利息收入500万美元,高于上年同期的370万美元;非利息支出2,220万美元;效率比率30.9%;平均资产回报率1.69%、平均股本回报率16.18%。
董事长兼首席执行官 Li Yu 表示,三季度净利与每股收益低于二季度,主要受上季利息回收与本季利息冲回影响;当季存款增加7,770万美元、增幅1.2%,存款竞争与市场环境很可能延续到2027年;贷款管线正在增强,有望在第四季度实现稳健的贷款增长;不良贷款的处置在推进,但慢于预期,部分资产因受破产法院裁决影响推迟到第四季度或2027年第一季度解决。他还表示,美联储近期的加息应有利于该行净息差,因其资产负债表对利率敏感。
资产负债表方面,截至9月30日,该行总资产78.2亿美元,较2025年底增加2.149亿美元;贷款总额62.5亿美元,与二季度末基本持平、较2025年底增加2.006亿美元;存款总额65.5亿美元,环比增加7,770万美元、较2025年底增加2.044亿美元。资产质量方面,不含待售贷款的不良贷款与逾期90天以上仍计息贷款合计1.094亿美元,高于6月30日的9,890万美元与2025年底的5,130万美元;其中当季列入不良的5,670万美元综合用途物业贷款已签约按面值出售、预计10月下旬交割,该行称该商业地产组合平均贷款价值比为60.8%、目前未发现重大损失内容。信贷损失准备覆盖率为贷款的1.26%。资本方面,有形普通股权益比率10.13%、杠杆比率10.78%、普通股一级资本比率11.26%、总资本比率13.93%。
Preferred Bank 总行位于洛杉矶(Los Angeles),在加州设有13家全功能分行(Alhambra、Century City、City of Industry、Torrance、Arcadia、Irvine 两家、Diamond Bar、Pico Rivera、Tarzana、Cupertino 与旧金山(San Francisco)两家),另在纽约设有曼哈顿与 Flushing 两家分行、在德州 Sugar Land 设有一家分行,存款由联邦存款保险公司 FDIC 承保。该行10月23日下午就三季度业绩举行电话会议。
Preferred Bank Reports Third-Quarter Net Income of $32.9 Million as Interest Reversals Weigh on Net Interest Income
Preferred Bank (NASDAQ: PFBC), headquartered in Los Angeles, California, reported results on October 23 for the quarter ended September 30, 2026. Net income was $32.9 million, or $2.73 per diluted share, a decrease of $3.0 million from the same quarter last year and $592,000 from the previous quarter. The bank is one of the larger independent commercial banks headquartered in California; originally founded as a Chinese-American bank, it now draws most of its customers from the diversified mainstream market, with branches in cities including Alhambra, City of Industry, Irvine and Diamond Bar.
Net interest income before provision for credit losses was $66.7 million, down $4.6 million from a year earlier and $3.3 million from the prior quarter. The net interest margin contracted to 3.49%, from 3.73% in the second quarter and 3.92% a year earlier. The bank said the decline was driven mainly by a $2.1 million interest income reversal after it placed a $56.7 million loan and four others totaling $13.5 million on nonaccrual status, compared with $2.9 million of interest recoveries recorded in the second quarter; a higher coupon on its subordinated debt, which moved to a floating rate of three-month SOFR plus 278 basis points on June 16 and carried a 6.44% coupon in the third quarter, also raised interest expense. Noninterest income rose to $5.0 million from $3.7 million a year earlier, noninterest expense was $22.2 million, the efficiency ratio was 30.9%, return on average assets was 1.69% and return on average equity was 16.18%.
Chairman and CEO Li Yu said third-quarter results were lower than the second quarter mainly because of last quarter's interest recoveries and this quarter's reversals. Deposits increased $77.7 million, or 1.2%, and he said competition for deposits and market conditions will likely continue into 2027. Loans excluding loans held for sale decreased $41.0 million after the $56.7 million loan was placed into held-for-sale status, but the bank is seeing a stronger pipeline that it hopes will produce solid loan growth in the fourth quarter. Resolution of nonaccrual loans is progressing more slowly than hoped, with several resolutions delayed to the fourth quarter or the first quarter of 2027 because the assets are subject to bankruptcy court decisions. He added that the recent Federal Reserve rate increase should benefit the bank's net interest margin because its balance sheet is asset sensitive.
Total assets were $7.82 billion at September 30, 2026, up $214.9 million from December 31, 2025. Gross loans were $6.25 billion, essentially flat from June 30 and up $200.6 million from year-end 2025. Total deposits were $6.55 billion, up $77.7 million from June 30 and $204.4 million from December 31, 2025. Nonaccrual loans and loans 90 days or more past due and still accruing totaled $109.4 million excluding loans held for sale, compared with $98.9 million at June 30, 2026 and $51.3 million at December 31, 2025. The $56.7 million mixed-use property loan placed on nonaccrual during the quarter is under contract to be sold at par, with closing anticipated in late October 2026; the bank said the average loan-to-value ratio for that commercial real estate cohort stands at 60.8% and no significant loss content has been identified. The allowance for credit losses was 1.26% of total loans held for investment. The tangible common equity ratio was 10.13%, the leverage ratio 10.78%, the common equity Tier 1 ratio 11.26% and the total capital ratio 13.93%.
Preferred Bank conducts business from its main office in Los Angeles and thirteen full-service branches in California (Alhambra, Century City, City of Industry, Torrance, Arcadia, two in Irvine, Diamond Bar, Pico Rivera, Tarzana, Cupertino and two in San Francisco), two branches in New York (Manhattan and Flushing, Queens) and a branch in Sugar Land, Texas. Its deposits are insured by the Federal Deposit Insurance Corporation (FDIC). The bank held a conference call on the afternoon of October 23 to discuss the results.
来源:GSM·美国(原文链接)
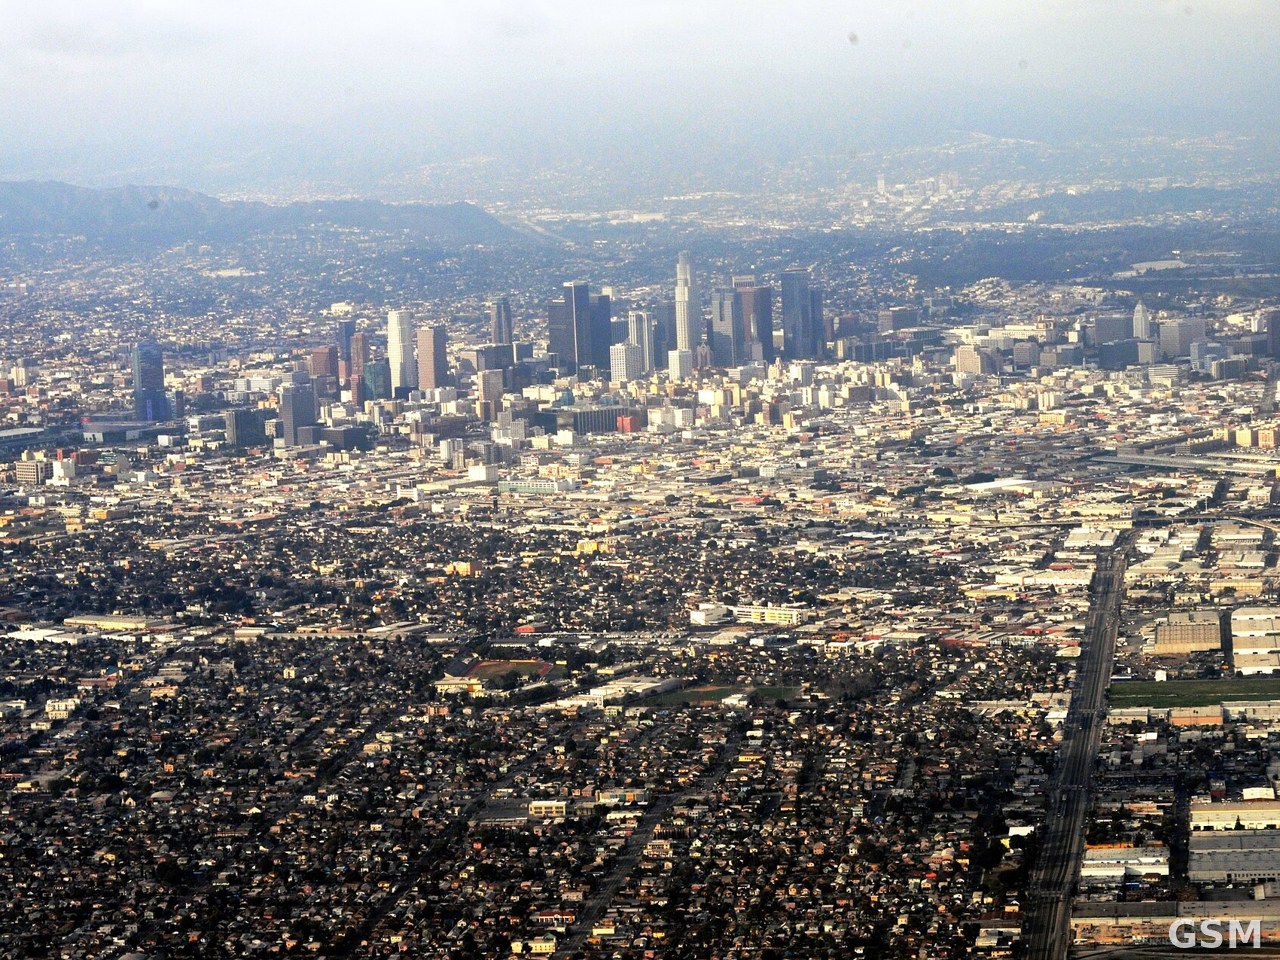
图片来源:洛杉矶(Los Angeles)市中心航拍,Preferred Bank 总部所在地(资料图)。Joe Mabel 摄,CC BY-SA 3.0,经 Wikimedia Commons 取用 / An aerial view of downtown Los Angeles, where Preferred Bank is headquartered (file photo). Photo by Joe Mabel, CC BY-SA 3.0, via Wikimedia Commons