全球芯片公司排名榜:英伟达 1257 亿美元居首 美国 11 家入榜、中国仅中芯国际一家进前 20
GSM 本周编制的《全球芯片公司排名榜》显示,2025 年全球半导体总营收达 7,934 亿美元、同比增长 21.0%(Gartner);英伟达以 1,257 亿美元营收、同比增长 63.9% 居全球第一,单一公司市占率 15.8%。主榜前 10 名由 Gartner 于 2026 年 1 月发布,统计期为 2025 全年;第 11 至 20 名按各公司官方财报口径续排,财年划分不一、营收为美元约数。
存储厂商是这一年名次变动的主角。SK 海力士营收 606 亿美元、增长 37.2%,由第 4 名升至第 3 名;美光科技营收 415 亿美元、增长 50.2%,由第 7 名升至第 5 名。Gartner 指出,2025 年高带宽存储(HBM)占 DRAM 市场的 23%、销售额超过 300 亿美元,AI 处理器销售额超过 2,000 亿美元。英特尔营收 479 亿美元、下降 3.9%,是前 10 名中唯一负增长的公司,名次由第 3 降至第 4。三星电子以 725 亿美元居第 2 名;高通、博通、AMD、苹果分列第 6 至第 9 名;联发科以 185 亿美元居第 10 名。
按总部所在地计,美国公司共 11 家进入前 20 名,其中 7 家进入前 10 名,合计营收约 3,872 亿美元;仅前 10 名中的 7 家美国公司合计就达 3,435 亿美元,占全球半导体总营收的 43.3%。中国公司在主榜上只有中芯国际一家:第 16 名,2025 年营收 93.3 亿美元、同比增长 16.2%。
榜单另设口径注记:台积电因属纯晶圆代工企业,未列入 Gartner 供应商主榜;按其公司财报,2025 年营收约 1,229 亿美元,若按金额计入可居全球第 2 位、仅次于英伟达。苹果的 246 亿美元为 Gartner 对其自研芯片价值的估算,苹果芯片不对外销售。
分榜呈现另一幅图景。晶圆代工方面(TrendForce,2026 年第二季度),台积电单季营收约 402 亿美元、份额 72.5%;中芯国际以 30.1 亿美元居第 3 名、份额 5.4%,环比增长 20.0%,与第 2 名三星代工厂(5.9%)的差距收窄至 0.5 个百分点;联电、格芯分列第 4、第 5 名,中国的华虹集团与晶合集成居第 6 与第 9 名,中国三家代工厂合计占前 10 家营收的 8.5%。
存储分榜上(TrendForce,2026 年第二季度),DRAM 单季营收 1,547.3 亿美元、环比增长 59.5%:三星份额 39.4% 居首,SK 海力士 24.9%,美光 23.3%,三家合计 87.6%;长鑫存储以 9.5% 居第 4 名,为前四中唯一的中国公司。HBM 单项营收份额 SK 海力士约 50%、三星约 33%、美光约 18%。NAND 闪存方面(Counterpoint,2026 年第二季度),三星居首,长江存储营收份额升至 14%,按比特出货量计居全球第 3 位。
手机应用处理器出货份额(Counterpoint,2026 年第二季度)由联发科以 31% 居首,高通 23%、苹果 19% 次之,紫光展锐以 13% 居第 4 名、华为海思以 5% 居第 6 名,中国两家合计占 18%。桌面独立显卡出货(Jon Peddie Research,2026 年第二季度)英伟达份额约 90%。中国数据中心 AI 加速器市场(IDC,2026 年上半年,经路透社报道)上半年总出货约 200.8 万颗:英伟达份额由上年同期 55% 降至 34%,华为昇腾以 28% 居第 2 名。微控制器分榜(Omdia,2025 年)英飞凌以 23.2% 居首,恩智浦、瑞萨、意法半导体与微芯同列前五、前五家合计约占八成。
榜单编制方注明,不同机构的统计口径(营收、出货量、比特量、财年划分与集团合并范围)存在差异,跨榜数字不可直接相加;本榜为公开数据汇编,不构成投资建议。
Global Chip Rankings: NVIDIA Tops the List at $125.7 Billion; 11 US Firms in the Top 20, SMIC China's Lone Entry
NVIDIA is the world's largest semiconductor company by revenue, with $125.7 billion in 2025 sales, up 63.9%, for a 15.8% market share, according to GSM's Global Chip Company Rankings compiled this week from Gartner data and company filings. Global semiconductor revenue reached $793.4 billion in 2025, up 21.0% (Gartner). The top 10 follows Gartner's ranking published in January 2026 for calendar 2025; ranks 11 to 20 are compiled from company financial reports, with differing fiscal years and revenues rounded to US dollars.
Memory makers posted the biggest moves. SK hynix rose from No. 4 to No. 3 with $60.6 billion, up 37.2%, and Micron Technology climbed from No. 7 to No. 5 with $41.5 billion, up 50.2%. Gartner noted that high-bandwidth memory (HBM) accounted for 23% of the DRAM market in 2025 with sales above $30 billion, while AI processor sales exceeded $200 billion. Intel fell from No. 3 to No. 4 with $47.9 billion, down 3.9% — the only decline in the top 10. Samsung Electronics ranked No. 2 at $72.5 billion, followed by Qualcomm, Broadcom, AMD and Apple in sixth through ninth place, and MediaTek at No. 10 with $18.5 billion.
By headquarters, 11 US companies made the top 20 and seven made the top 10, with combined revenue of about $387.2 billion; the seven US firms in the top 10 alone accounted for $343.5 billion, or 43.3% of the global total. SMIC is China's only entry on the main list, at No. 16 with $9.33 billion in 2025 revenue, up 16.2%.
The rankings carry a methodology note: TSMC, a pure-play foundry, is excluded from Gartner's vendor ranking; on its reported 2025 revenue of about $122.9 billion it would rank No. 2 globally, behind only NVIDIA. Apple's $24.6 billion is Gartner's estimate of the value of its in-house chips, which are not sold externally.
Segment rankings tell a more distributed story. In foundry (TrendForce, Q2 2026), TSMC held a 72.5% share on quarterly revenue of about $40.2 billion; SMIC ranked No. 3 with $3.01 billion and a 5.4% share, up 20.0% quarter on quarter, narrowing the gap to second-placed Samsung Foundry (5.9%) to 0.5 percentage points. UMC and GlobalFoundries ranked fourth and fifth, while China's HuaHong Group and Nexchip ranked sixth and ninth; the three Chinese foundries together took 8.5% of the top 10's revenue.
In memory (TrendForce, Q2 2026), DRAM revenue jumped 59.5% quarter on quarter to $154.73 billion: Samsung led with 39.4%, SK hynix held 24.9% and Micron 23.3% — 87.6% combined — while CXMT ranked fourth at 9.5%, the only Chinese company in the top four. In HBM revenue, SK hynix held about 50%, Samsung about 33% and Micron about 18%. In NAND flash (Counterpoint, Q2 2026), Samsung led, while YMTC's revenue share rose to 14% and it ranked third globally by bit shipments.
MediaTek led smartphone application-processor shipments with 31% (Counterpoint, Q2 2026), ahead of Qualcomm at 23% and Apple at 19%; China's Unisoc ranked fourth at 13% and HiSilicon sixth at 5%, for a combined 18%. NVIDIA took about 90% of desktop discrete GPU shipments (Jon Peddie Research, Q2 2026). In China's data center AI accelerator market (IDC, first half of 2026, reported by Reuters), shipments totaled about 2.008 million units: NVIDIA's share fell from 55% a year earlier to 34%, while Huawei's Ascend line rose to second place at 28%. In microcontrollers (Omdia, 2025), Infineon led with 23.2%, with NXP, Renesas, STMicroelectronics and Microchip completing a top five that together holds about 80%.
The compiler notes that methodologies differ across research firms — revenue, unit and bit bases, fiscal years and consolidation scopes — so figures across tables are not directly additive. The rankings are a compilation of public data and do not constitute investment advice.
来源:GSM·美国(原文链接)
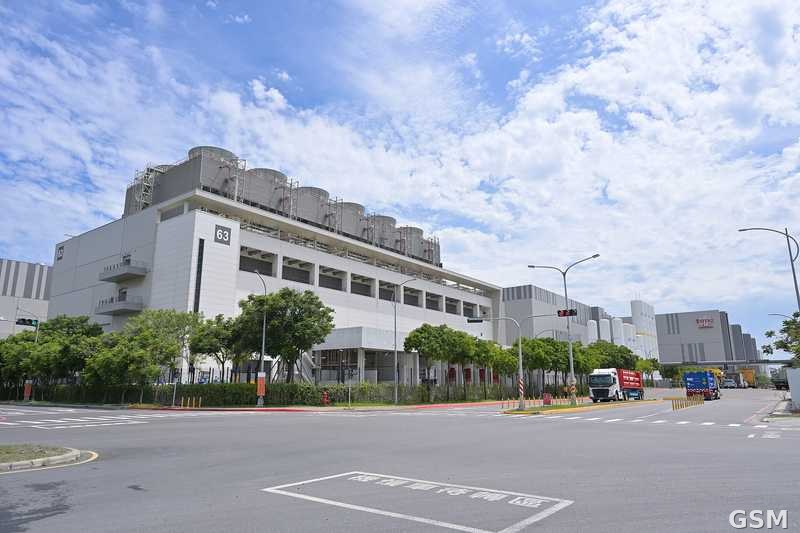
图片来源:图:台积电位于南部科学园区的 Fab 18 晶圆厂。照片:4300streetcar,CC BY 4.0,经 Wikimedia Commons。Photo: TSMC's Fab 18 in the Southern Taiwan Science Park. Photo: 4300streetcar, CC BY 4.0, via Wikimedia Commons.