三季报季开锣日六家巨头同日交卷:高盛利润增29%大超预期,摩根大通罕见未达预期,花旗创十年最佳三季度营收
纽约——美国三季度财报季10月13日(周二)正式开锣,摩根大通、富国银行、高盛、花旗四家大行与强生、联合健康同日在盘前交卷。六家机构的数字拼出的图景并不一致:交易与投行业务在动荡市况中普遍赚钱,但「超预期」与「未达预期」同日出现,利率与债市波动正在重新给银行股定价。
高盛是当天最亮眼的一家。第三季度净利润52.9亿美元、每股17.01美元,同比分别高于去年同期的41.0亿美元与12.25美元,远超LSEG汇总的分析师预期(每股13.02美元);净营收186.8亿美元,为公司史上第二高的季度水平,年化普通股股本回报率18.7%。引擎是股票交易:中东冲突、美联储9月加息与芯片股抛售让市场剧烈波动,投资者大举调仓,高盛股票业务收入同比大涨72%至64.4亿美元;固定收益、外汇与大宗商品(FICC)收入则同比微降1%至34.7亿美元。首席执行官所罗门(David Solomon)在声明中表示,尽管环境复杂,客户仍在向高盛寻求建议与融资服务,公司有能力继续交付。背景数字值得一提:LSEG数据显示,全球并购额三季度环比下降41%至9,930亿美元,为2025年二季度以来首次跌破1万亿美元——交易台的繁荣,是在并购降温的底色上发生的。摩根大通则交出了一份罕见的「未达预期」。三季度净利润153亿美元、每股5.57美元(去年同期144亿美元、5.07美元),市场业务收入同比增15%、投行费用增14%;但每股盈利低于市场预期的5.90美元、营收509.1亿美元亦低于预期的512.2亿美元,固定收益交易收入比预期少了约5.5亿美元。首席执行官戴蒙(Jamie Dimon)当天警告,若利率再上升一个百分点,全美的财务痛感将进一步加重——这句话在债市收益率处于高位的当下,分量不轻。
花旗的故事是「利润大涨、股价却跌」。三季度净利润52.5亿美元、每股2.85美元,同比大增40%(去年同期38亿美元、1.86美元;去年基数受剥离墨西哥Banamex的商誉减值拖低);营收同比增8%至238.5亿美元,首席执行官范洁恩(Jane Fraser)称这是花旗十年来最好的三季度营收。投行收入同比增9%至13.5亿美元,但交易收入同比仅增2%、环比大跌27%,股价盘前下跌约1.4%。花旗当季向股东返还41亿美元,年内回购累计已达133亿美元,有形普通股股本回报率11.5%,已跑赢其11%的年度目标。
富国银行走的是资产负债表修复路线:净利润59.5亿美元、每股1.87美元(去年同期55.9亿美元、1.66美元),净利息收入同比增5%至125.2亿美元;资产上限解除后,贷款扩张空间打开,财富管理部门净利润同比增19%至6.03亿美元、客户资产升至2.45万亿美元。
非银两家同样有看点。强生营收254亿美元、调整后每股2.59美元,双双小幅高于预期,银屑病药Tremfya销售大涨68%至24亿美元、老牌药Stelara则下滑54%至7.16亿美元,中东冲突拖累了其医疗器械的海外销售。联合健康调整后每股4.69美元,明显高于预期的4.14美元,并把2026年调整后每股盈利指引从「至少19.50–20美元」上调至「至少20.50美元」,医疗成本率88.4%、优于去年同期的89.90%,盘前股价上涨约4.5%。
美国银行与摩根士丹利定于周三(10月14日)接力发布三季报。
Six Giants Report on Earnings Season's Opening Day: Goldman Profit Jumps 29%, JPMorgan Posts a Rare Miss, Citi Books Its Best Third-Quarter Revenue in a Decade
New York — The U.S. third-quarter earnings season officially opened on Tuesday, October 13, with JPMorgan, Wells Fargo, Goldman Sachs and Citi — four big banks — reporting before the bell on the same day as Johnson & Johnson and UnitedHealth. The six companies' numbers did not draw a consistent picture: trading and investment banking generally made money in turbulent markets, but 'beats' and 'misses' appeared on the same day, and interest-rate and bond-market volatility is repricing bank stocks.
Goldman Sachs was the day's standout. Third-quarter net income of $5.29 billion, or $17.01 a share, was up from $4.10 billion and $12.25 a share a year earlier and far above the LSEG analyst consensus of $13.02 a share; net revenue of $18.68 billion was the second-highest quarterly level in the company's history, with an annualized return on common equity of 18.7%. The engine was equities trading: Middle East conflict, a September Fed rate hike and a chip-stock selloff made markets swing violently, investors repositioned heavily, and Goldman's equities revenue jumped 72% year on year to $6.44 billion, while fixed income, currencies and commodities (FICC) revenue eased 1% to $3.47 billion. Chief Executive David Solomon said in a statement that despite a complex environment, clients continue to seek Goldman's advice and financing, and the firm is able to keep delivering. A background figure is worth noting: LSEG data show global M&A volume fell 41% quarter on quarter in the third quarter to $993 billion, below $1 trillion for the first time since the second quarter of 2025 — the trading boom happened against a backdrop of cooling deal-making.
JPMorgan, by contrast, delivered a rare 'miss.' Third-quarter net income was $15.3 billion, or $5.57 a share (a year earlier: $14.4 billion and $5.07), with markets revenue up 15% and investment banking fees up 14% year on year; but earnings per share came in below the $5.90 consensus and revenue of $50.91 billion also missed the expected $51.22 billion, with fixed-income trading revenue about $550 million lighter than expected. Chief Executive Jamie Dimon warned the same day that if interest rates rose by another percentage point, the financial pain across America would deepen further — a remark that carries weight while bond yields sit at elevated levels.
Citi's story was 'profits up sharply, shares down.' Third-quarter net income of $5.25 billion, or $2.85 a share, jumped 40% (a year earlier: $3.8 billion and $1.86, a base dragged down by a goodwill impairment on the divestiture of Banamex in Mexico); revenue rose 8% to $23.85 billion, which Chief Executive Jane Fraser called Citi's best third-quarter revenue in a decade. Investment banking revenue rose 9% to $1.35 billion, but trading revenue rose only 2% year on year and fell 27% from the previous quarter, and the shares slipped about 1.4% in premarket trading. Citi returned $4.1 billion to shareholders in the quarter, with buybacks for the year reaching $13.3 billion, and its return on tangible common equity of 11.5% has already run ahead of its 11% annual target.
Wells Fargo took the balance-sheet repair route: net income of $5.95 billion, or $1.87 a share (a year earlier: $5.59 billion and $1.66), with net interest income up 5% to $12.52 billion; with the asset cap lifted, room for loan growth has opened up, and wealth management net income rose 19% to $603 million, with client assets rising to $2.45 trillion.
The two non-banks had highlights as well. Johnson & Johnson posted revenue of $25.4 billion and adjusted earnings of $2.59 a share, both slightly ahead of expectations; psoriasis drug Tremfya sales surged 68% to $2.4 billion while legacy drug Stelara fell 54% to $716 million, and the Middle East conflict dragged on overseas sales of its medical devices. UnitedHealth's adjusted earnings of $4.69 a share clearly beat the expected $4.14, and it raised its 2026 adjusted EPS guidance from 'at least $19.50–$20' to 'at least $20.50'; its medical cost ratio of 88.4% was better than 89.90% a year earlier, and the shares rose about 4.5% in premarket trading.
Bank of America and Morgan Stanley are scheduled to follow with their third-quarter results on Wednesday, October 14.
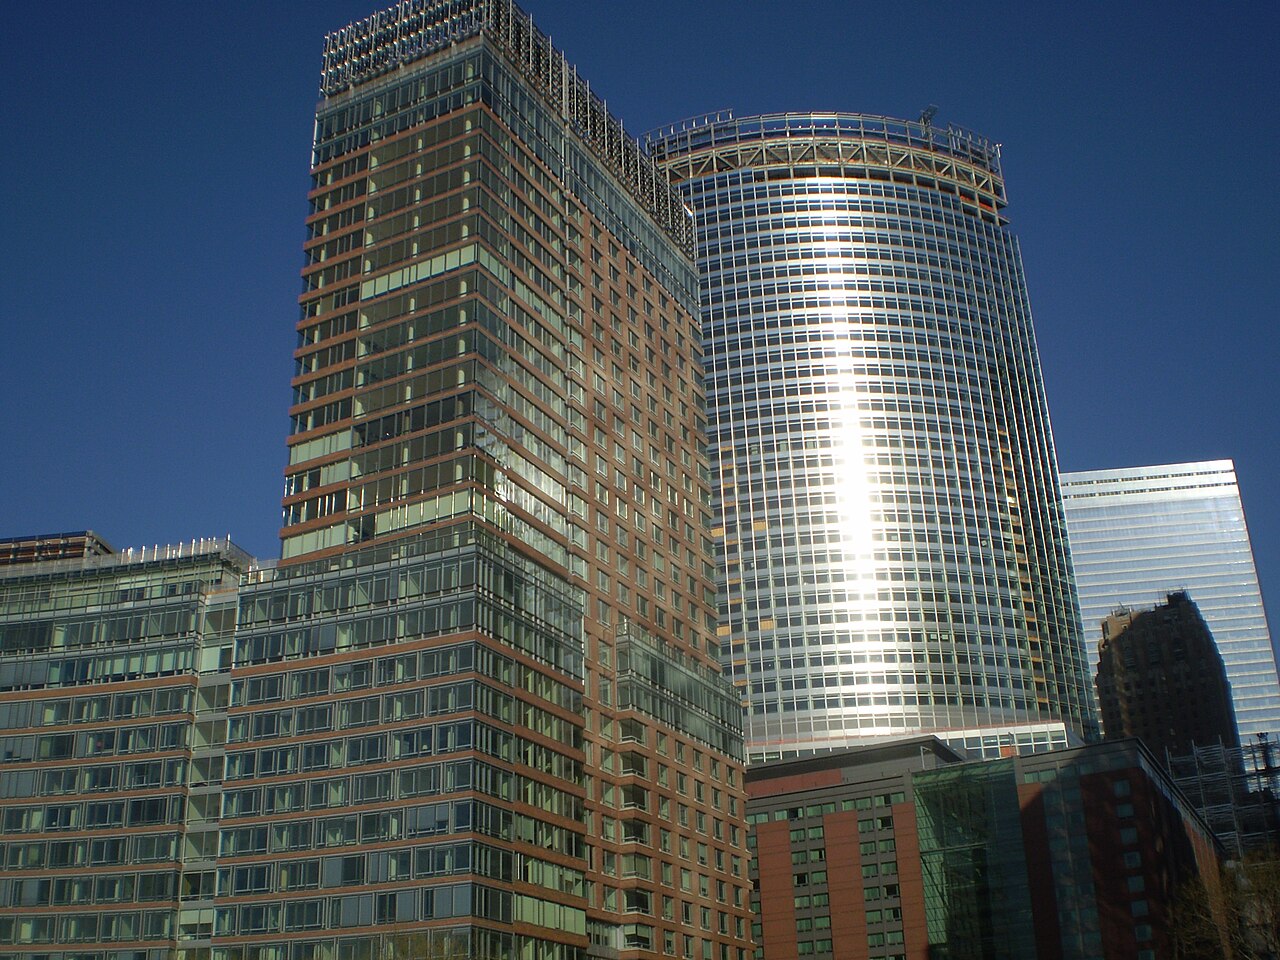
图片来源:高盛纽约总部大楼。公共领域,维基共享资源